

This week’s AI stock spotlight is V.F. Corporation ($VFC).
V.F. Corporation is one of the oldest names in American apparel, and very little of its portfolio today resembles where it started. The company was founded in 1899 in Reading, Pennsylvania, as the Reading Glove and Mitten Manufacturing Company. In 1920 it became Vanity Fair Silk Mills as it expanded into silk lingerie, and it carried the Vanity Fair name for decades before becoming VF Corporation. Over the following century it reinvented itself several times, from intimate apparel to jeans to the outdoor, action sports and workwear portfolio it owns today. The company is now headquartered in Denver, Colorado, employs about 26,000 people and has been led since July 2023 by President and Chief Executive Officer Bracken Darrell, who joined from Logitech, where he ran the business for ten years and was credited with a major turnaround.
The business model is that of a brand owner. VF designs, sources, markets and distributes branded apparel, footwear and accessories, and it earns revenue through two channels: wholesale accounts such as specialty retailers, department stores and national chains, and its own direct-to-consumer business through stores, concessions and e-commerce. In the first quarter of fiscal 2027, wholesale produced $931.0 million of revenue and direct-to-consumer produced $738.4 million. The company reports three segments. Outdoor is anchored by The North Face, Timberland, Smartwool, Icebreaker and Altra. Active is anchored by Vans, along with Kipling, Napapijri, Eastpak and JanSport. Work is built around Timberland PRO. In the most recent quarter, The North Face generated $590.9 million of revenue, Vans $459.8 million and Timberland $266.1 million.
The portfolio is smaller than it was two years ago, by design. VF completed the sale of Supreme to EssilorLuxottica on October 2, 2024, in a deal announced at $1.5 billion, and it closed the sale of Dickies to Bluestar Alliance for $600 million in cash on November 12, 2025. Both sales were part of the Reinvent program Darrell launched to simplify the company, cut costs and pay down debt. VF competes with Nike, Deckers Outdoor, Columbia Sportswear, Amer Sports, Skechers, Levi Strauss and Under Armour, among others. Its differentiation is breadth. Few competitors own a performance outdoor leader, a heritage boot brand and a global skate and youth culture brand under one roof, and that mix gives VF exposure to very different customers and seasons. It also means the company’s results depend heavily on whichever brand is struggling at the time, and for the past several years that brand has been Vans.
On October 13, 2026, VF closed at $16.07, up 1.77% on the day, after gapping open at $16.67 and trading as high as $16.87. The catalyst was a pair of analyst upgrades. Truist upgraded the stock from Hold to a bullish rating and raised its price target to $20 from $14, arguing that Vans is “poised to inflect” as fashion trends shift away from the long-dominant athletic look and new product launches gain traction. Piper Sandler upgraded the stock to Overweight from Neutral and raised its target to $20 from $16, writing that the key debate on the stock still centers on the Vans turnaround. Those calls followed a JPMorgan upgrade to Neutral from Underweight on October 9 and a Barclays target increase to $24 on October 12. The stock is relevant this week because of how far it has come in a short time. On September 10, 2026, VF touched its 52-week low of $12.46. It has gained 28.97% from that low in 23 trading sessions, and 11.21% in the past week alone.
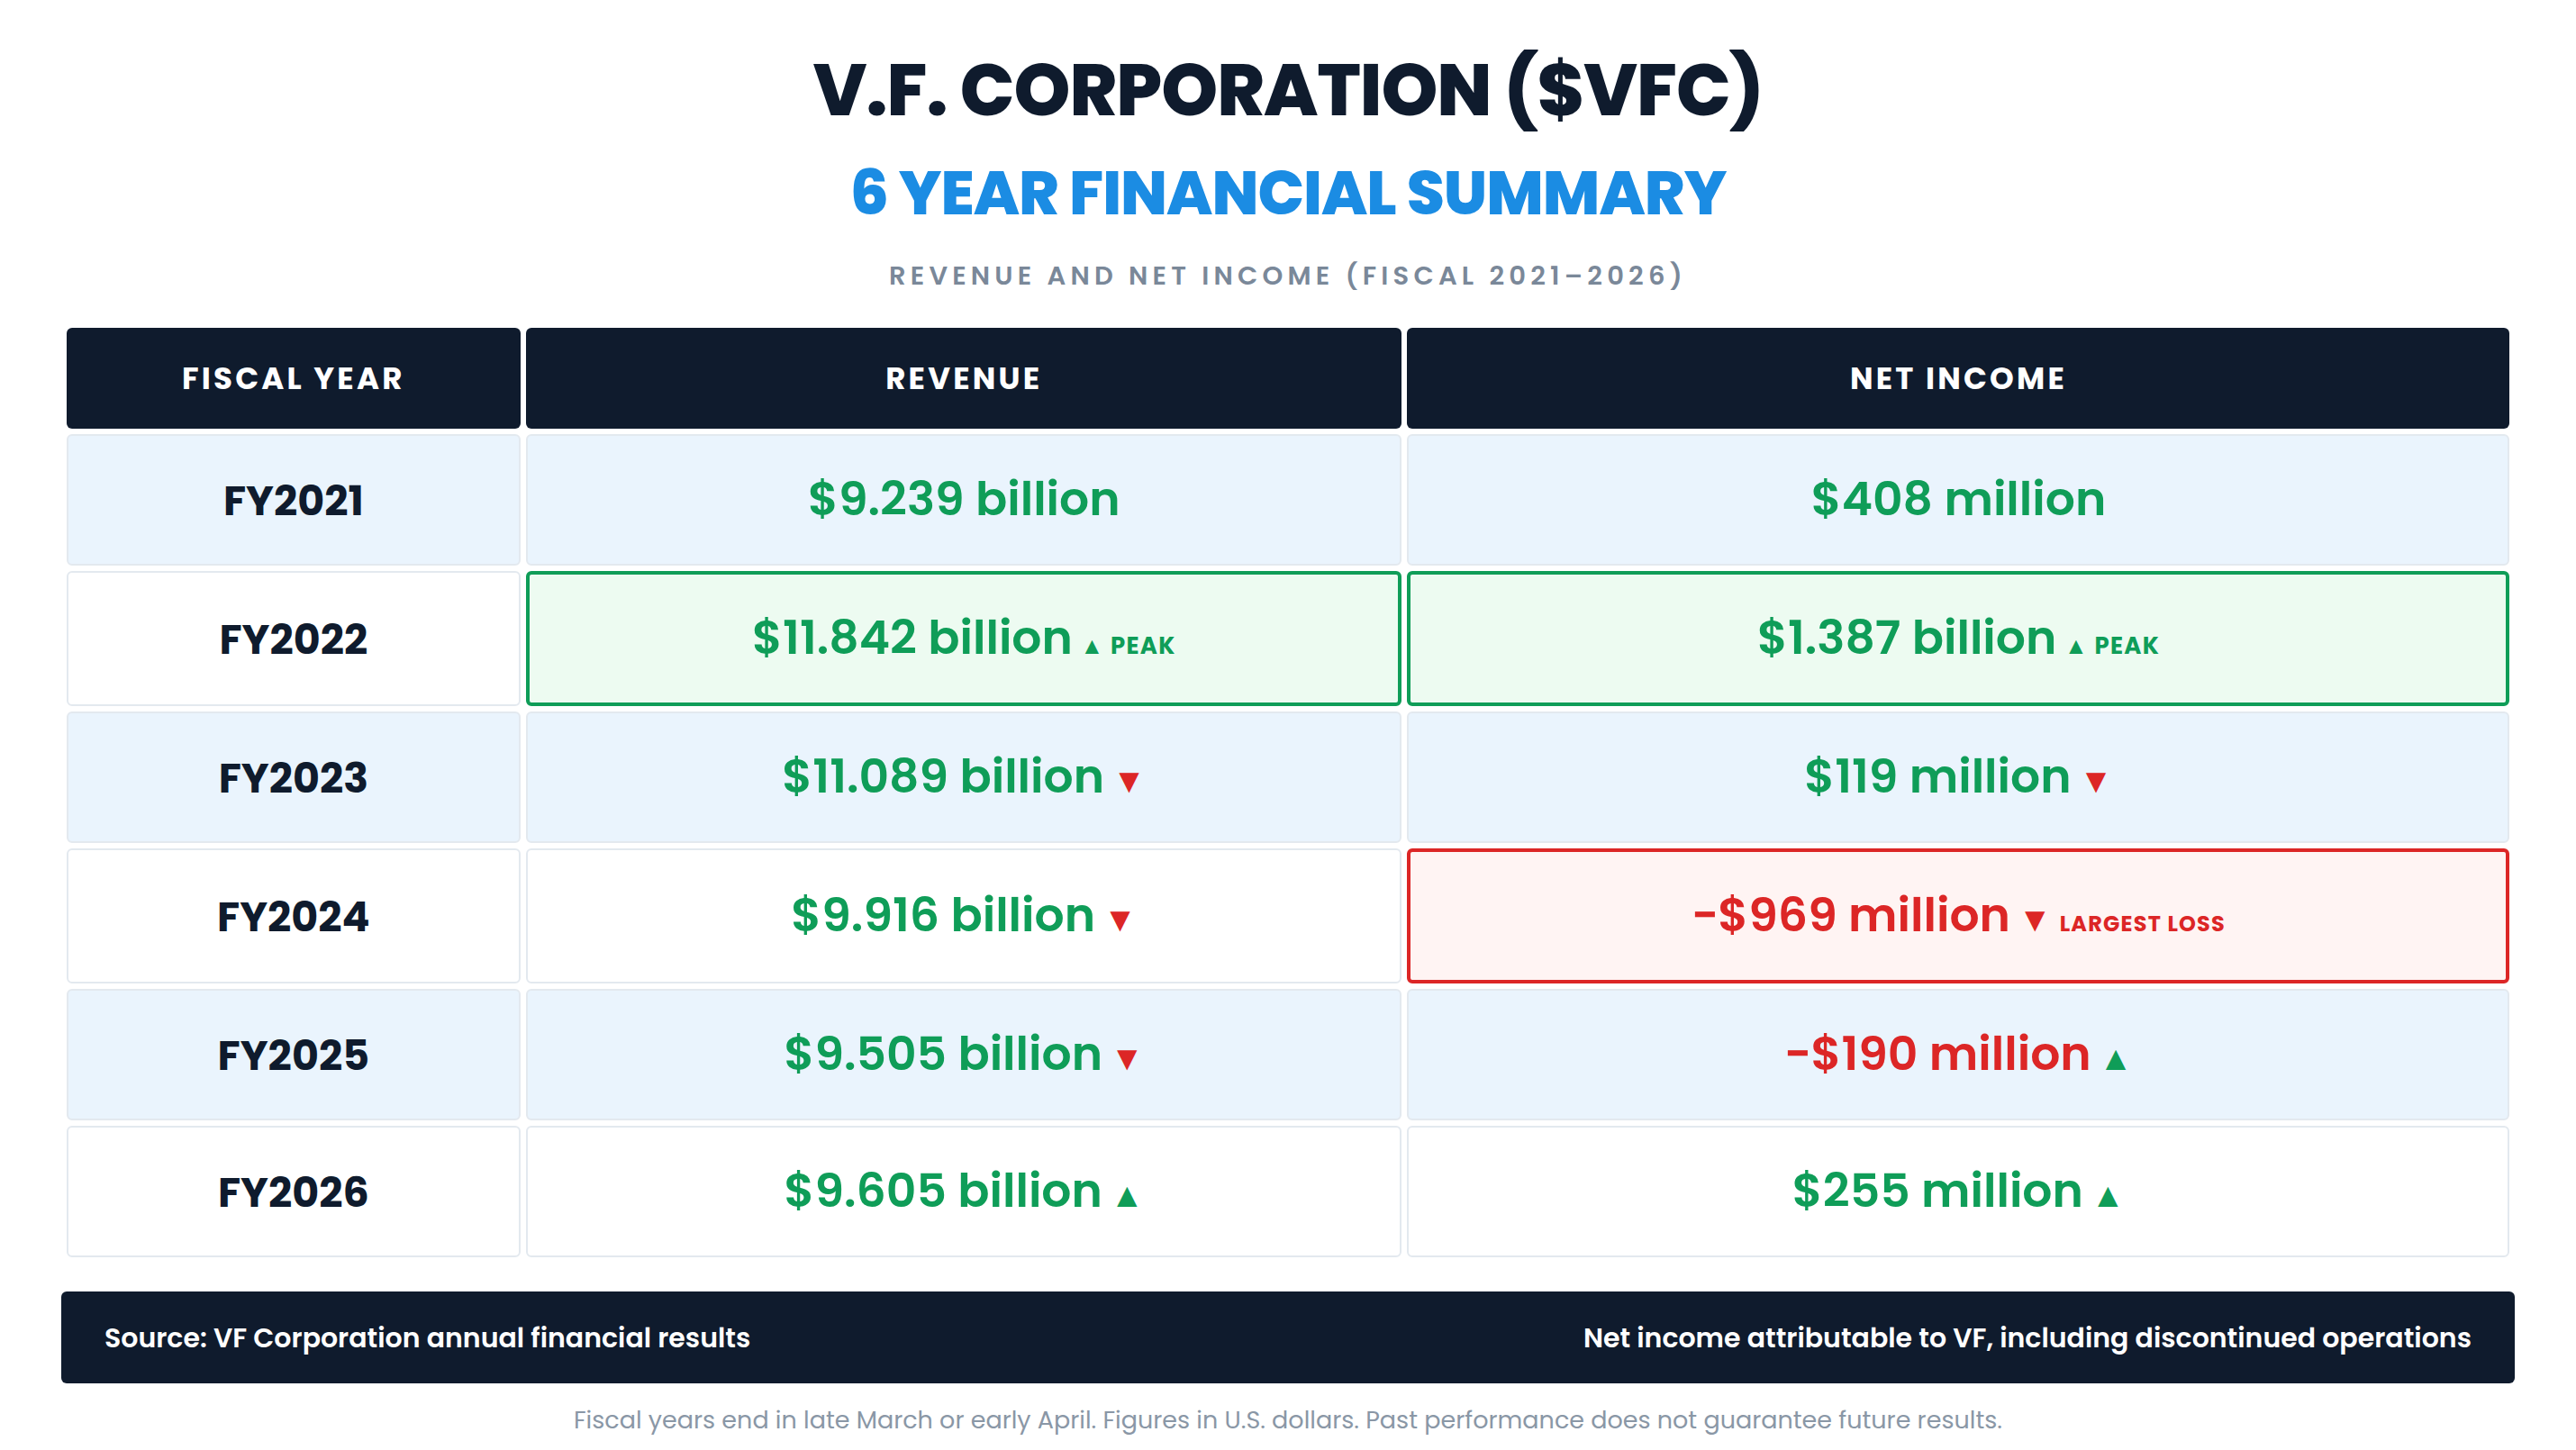
VF’s fiscal year ends in late March or early April, so fiscal 2026 covers roughly April 2025 through March 2026. Revenue was $9.239 billion in fiscal 2021, during the pandemic, and jumped 28.17% to a peak of $11.842 billion in fiscal 2022. Then it declined for three straight years: down 6.36% to $11.089 billion in fiscal 2023, down 10.58% to $9.916 billion in fiscal 2024 and down 4.14% to $9.505 billion in fiscal 2025. In fiscal 2026 it finally grew again, rising 1.05% to $9.605 billion. That return to growth is real, but fiscal 2026 revenue is still 18.89% below the 2022 peak.
Net income tells a harsher story. VF earned $408 million in fiscal 2021 and a peak of $1.387 billion in fiscal 2022, or $3.53 per diluted share. Profit collapsed to $119 million in fiscal 2023, and in fiscal 2024 the company lost $969 million, or $2.49 per share, the largest loss in the table. The loss narrowed to $190 million in fiscal 2025, and in fiscal 2026 VF returned to a profit of $255 million, or $0.64 per diluted share. The distinction matters. These figures include discontinued operations, which is where the results of divested brands such as Supreme were recorded. Discontinued operations reduced net income by $637 million in fiscal 2023 and by $259 million in fiscal 2025, so part of the damage in the table reflects the cost of exiting businesses rather than the earning power of the brands VF kept.
Here is the number the annual table hides. VF’s leverage ratio was 5.1 times at the end of fiscal 2024, 4.1 times at the end of fiscal 2025 and 3.1 times at the end of fiscal 2026. Management’s target for the end of fiscal 2027 is 2.6 to 2.9 times, and its medium-term goal is 2.5 times or lower by fiscal 2028. In the first quarter of fiscal 2027, net debt was down $1.1 billion, or 20%, from a year earlier. Fiscal 2026 free cash flow, excluding a $100 million pension termination impact, was $405 million, about 6.41% of VF’s market value of roughly $6.32 billion at the October 13 close, and reported operating margin expanded 280 basis points to 6.0%. The revenue line shows a company that shrank for three years. The balance sheet shows a company that has spent those years repairing itself.
The first quarter of fiscal 2027, reported on July 29, 2026, shows both sides of that story. Revenue was $1.669 billion, down 5% from $1.761 billion a year earlier, mainly because Dickies was no longer in the numbers. Excluding Dickies, revenue rose 1% and was flat in constant currency, ahead of guidance for a low-single-digit decline. The North Face grew 6%, Timberland grew 4% and direct-to-consumer revenue rose 2%. Vans fell 8%, as continued growth in its Americas direct-to-consumer business was more than offset by declines in global wholesale. Gross margin improved 100 basis points to 54.9%. The first quarter is seasonally VF’s smallest, and the company reported a net loss of $97.2 million, or $0.25 per diluted share. The adjusted loss of $0.27 per share missed the consensus estimate of a $0.22 loss, and the stock fell 17.37% that day, its largest single-session decline since April 2025. The company also announced a chief financial officer transition the same day.
What the quarter proves is that The North Face and Timberland are still growing and that the cost and margin work is holding. What it does not prove is that Vans has turned. Management raised its fiscal 2027 revenue outlook to growth of 2% or better in constant currency, from a prior range of 1% to 2%, kept its adjusted operating margin target at about 8% and guided free cash flow flat to up from $405 million. It also said it expects Vans wholesale to improve significantly in the second half of the year, and it expects Vans revenue to decline about 9% again in the second quarter before that improvement arrives.
Traders are really asking two questions now. First, is Vans actually at the inflection point that two analysts called this week, or is the upgrade cycle running ahead of the evidence? Second, can VF keep cutting debt and expanding margins while the brand that once drove its growth is still shrinking?
The bullish evidence is concrete. VF returned to full-year revenue growth in fiscal 2026 for the first time in three years, and the fourth quarter was its strongest revenue performance since Darrell joined. Vans returned to growth in its Americas direct-to-consumer business for the first time in more than four years. The leverage ratio has dropped two full turns in two years, and two divestitures have brought in roughly $2.1 billion of announced deal value. Management has reaffirmed its medium-term target of a 10% operating margin exit rate in fiscal 2028. The analyst tone has shifted as well: four firms have moved their rating or target higher in the past week, and the bullish camp now has four members, up from two before the October upgrades.
That is also where the market could be wrong. The main risk case has three parts. The first is Vans itself. A turnaround thesis built on fashion cycles and new product launches is difficult to verify in real time, and Vans wholesale is still declining. The second is execution through a leadership change. VF is changing chief financial officers in the middle of a turnaround, and the most recent quarter was an earnings miss. The third is the stock’s own behavior. From its April 21, 2026 high of $22.27, VF fell 44.05% to its September 10 low, despite reinstated guidance and a return to annual revenue growth. The biggest risk is that the story is wearing a convincing disguise: a rally driven by upgrades and fashion-trend arguments can look like fundamental confirmation until the next set of results arrives.
The near-term catalyst calendar is clear. Second-quarter fiscal 2027 results are scheduled for October 28, 2026, with the release expected around 6:00 a.m. Eastern and a conference call at 8:00 a.m. Consensus calls for earnings of $0.53 per share on revenue of $2.66 billion, compared with $0.52 and $2.80 billion a year earlier. Traders should watch Vans revenue against the roughly 9% decline management guided to, any update on the second-half wholesale recovery, The North Face, which management expected to be roughly flat in the quarter, free cash flow and progress toward the year-end leverage target. VF pays a regular quarterly dividend of $0.09 per share, or $0.36 annualized, which works out to a yield of about 2.24% at the October 13 close. The most recent payment was made on September 17, 2026, to shareholders of record on September 10. The regular quarterly rate was $0.30 in early 2023 before it was reduced to $0.09 in the December 2023 quarter, and VF has not paid a special dividend over the past twelve months.
This setup suits swing traders and active position traders who are comfortable with a stock that can move several percent in a session on analyst calls or earnings. Over the past 20 sessions, VF’s average daily range has been 3.80% of its closing price. It is less suitable for traders looking for a steady income stock, or for anyone who assumes a century-old apparel company must be a slow mover. The same shares fell 28.74% in a single session on April 3, 2025, rose 27.52% on April 9, 2025, and fell 17.37% on July 29, 2026.
The early-warning signal to watch is the October 13 reversal. The stock gapped up to $16.67, above the prior close of $15.79, traded as high as $16.87 and then faded to close at $16.07, after dipping as low as $15.74 during the session, below the prior close. In other words, the gap opened and was filled on the same day. If the upgrade rally has real support, the $15.79 area should hold. A close below $15.79 would tell you that the market has stopped paying for the upgrades and that the stock is back to waiting for October 28.
So the picture heading into this week is a company with a repaired balance sheet, growing outdoor brands and a stock that has snapped back hard from a deep decline on improving analyst sentiment. The trend says stay interested. The volatility says stay alert. With that in mind, here is what the professional analyst community currently expects.
Wall Street Analysts Annual Forecasts
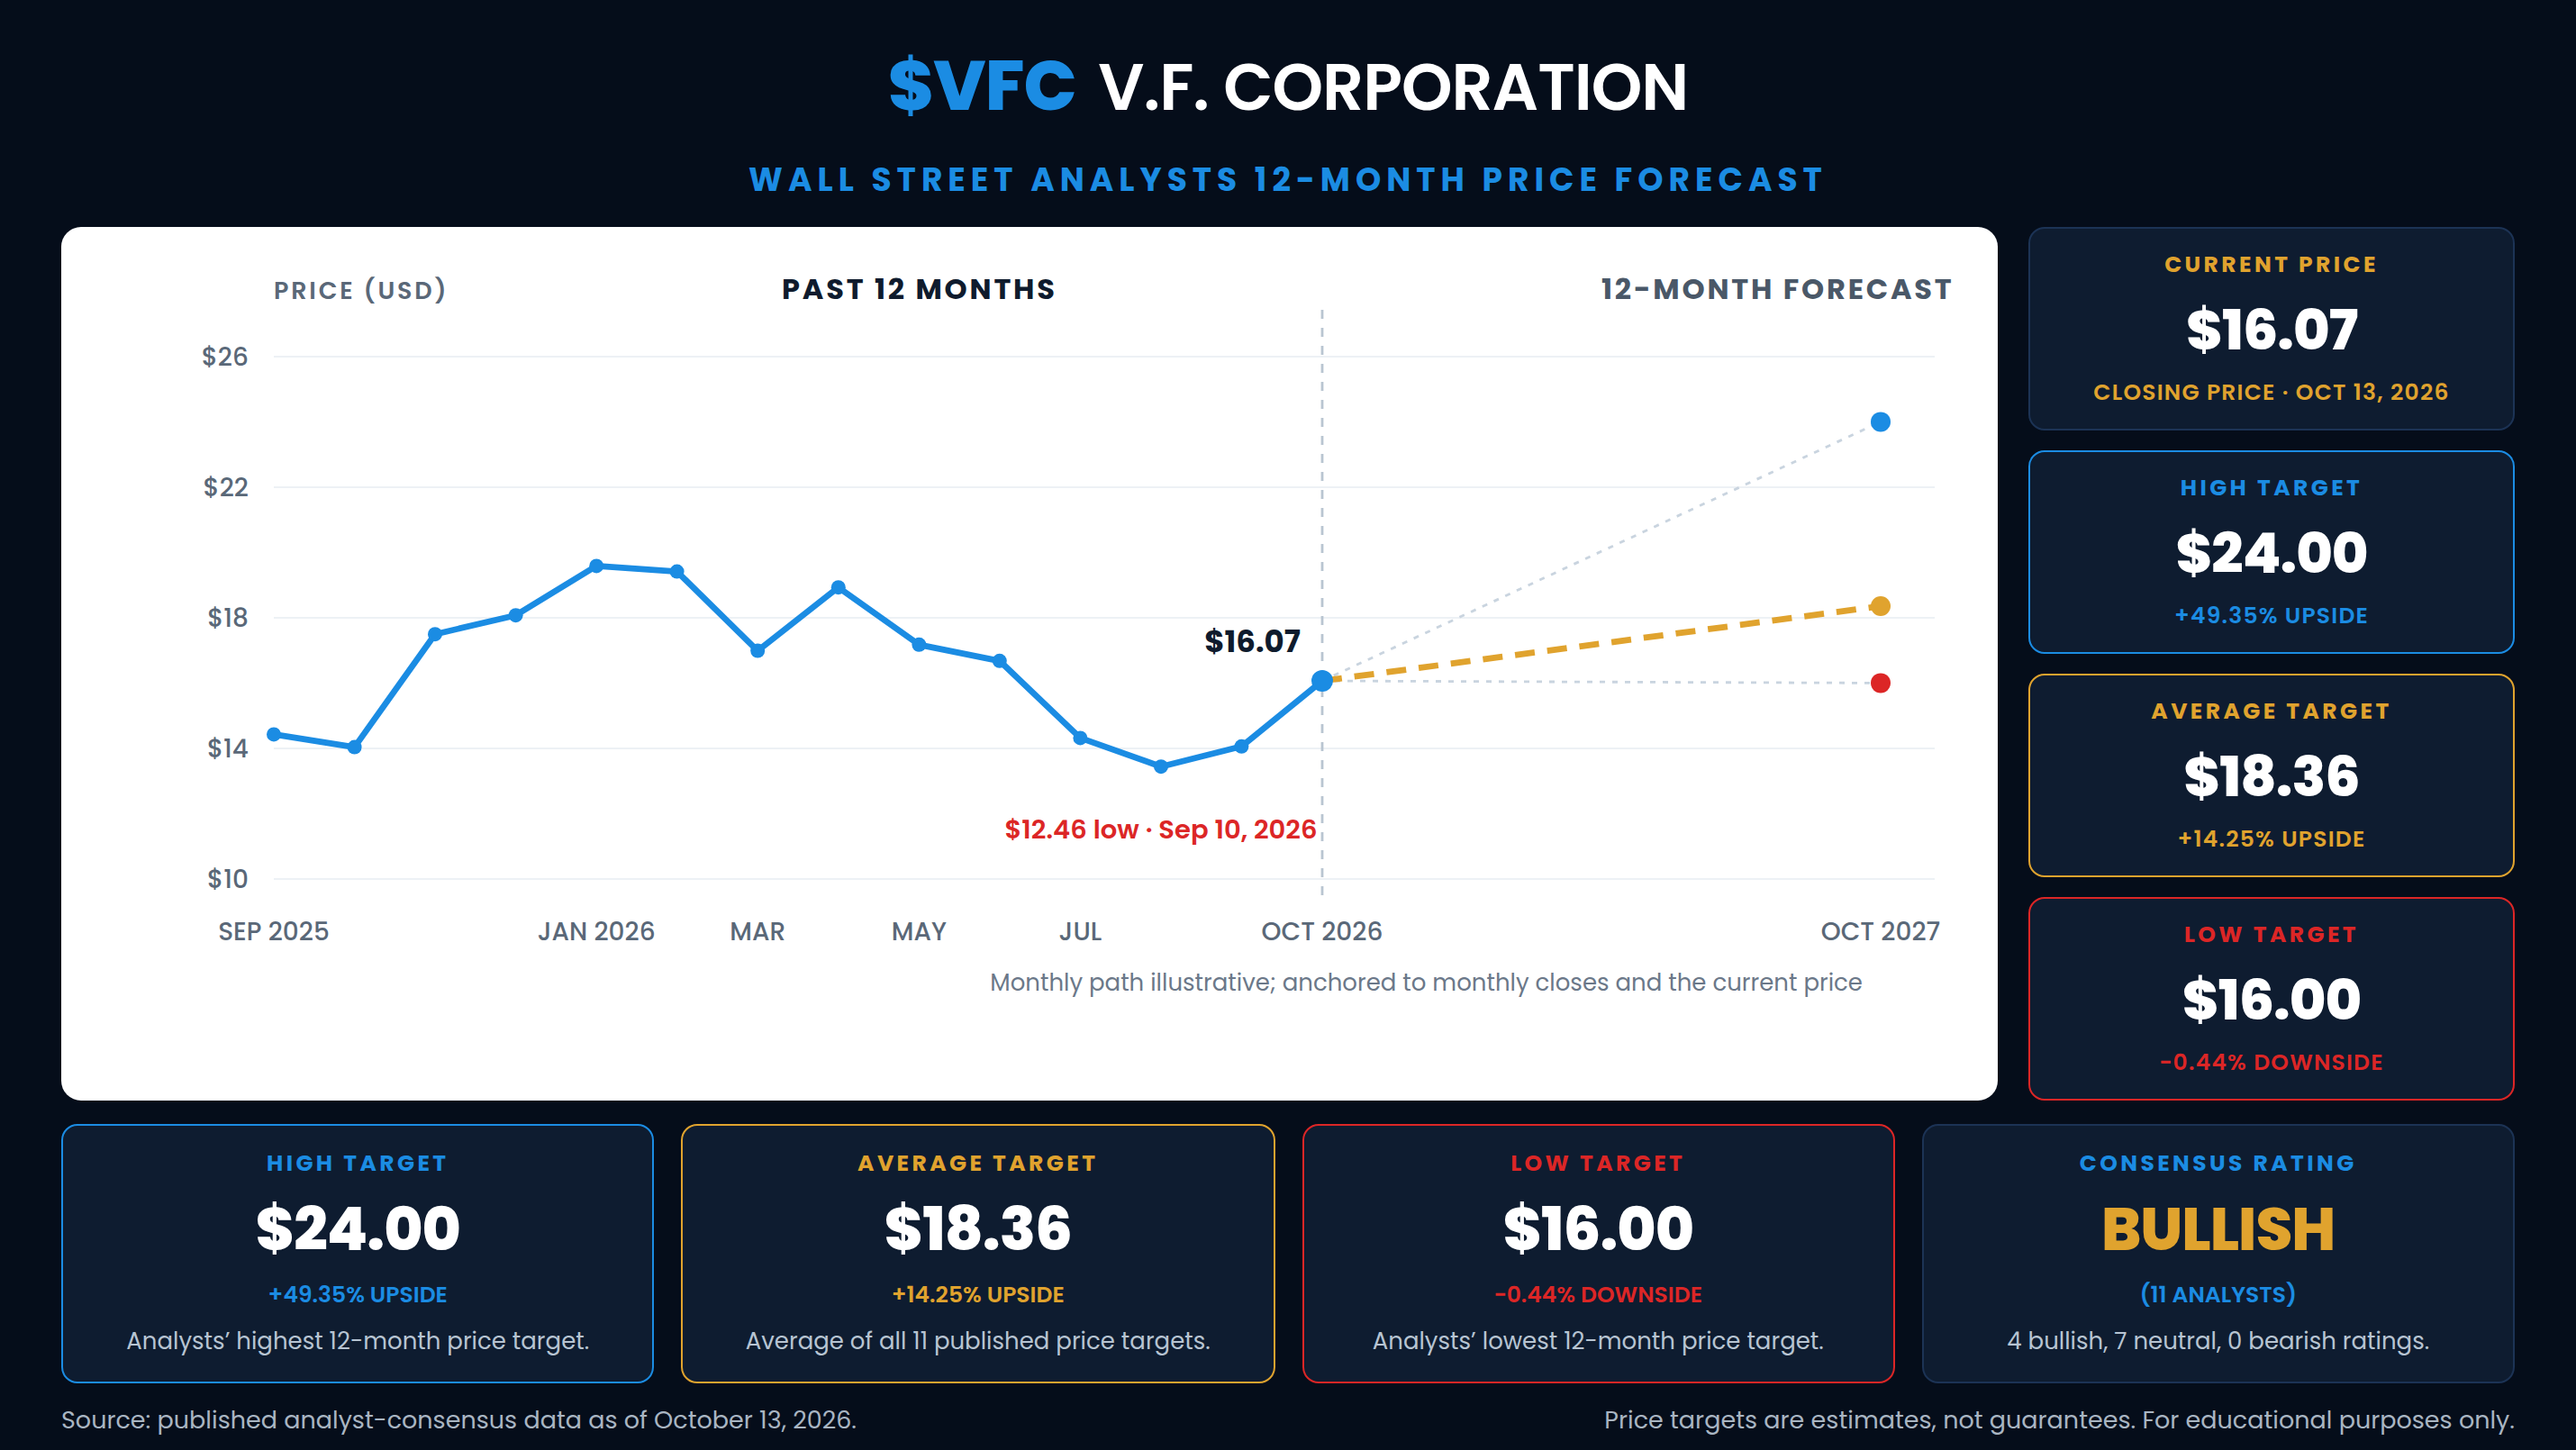
Eleven analysts are included in the published consensus for V.F. Corporation, and the consensus leans bullish, with four bullish ratings, seven neutral ratings and no bearish ratings. The average 12-month price target is $18.36, the median target is $18.00, the high target is $24.00 and the low target is $16.00.
Measured against the October 13, 2026 close of $16.07, the average target implies a 14.25% gain. The median target implies a 12.01% gain. The high target implies a 49.35% gain. The low target sits just below the current price, implying a 0.44% decline. The spread between the high and low target is $8.00, which is 49.78% of the current share price.
The revision trail adds important context. The $24 high target belongs to Barclays, which holds an Overweight rating and raised its target from $23 on October 12, 2026. Needham holds a bullish rating with a $21 target, which it cut from $25 on July 29, the day of the first-quarter report. Truist and Piper Sandler, the two upgrades this week, both sit at $20. On the neutral side, JPMorgan upgraded the stock to Neutral from Underweight on October 9 with an $18 target, and Citigroup holds a Neutral rating at $18. The $16 low targets come from UBS, Goldman Sachs, Evercore ISI and Wells Fargo, all of which cut their targets on July 30, the day after the earnings miss, and Stifel holds a Hold rating at $17.
The practical takeaway is that the analyst community has shifted from cautious to constructive in a matter of days, but most of the neutral targets were set in late July and have not yet been updated. That deserves to be read carefully. Five of the eleven targets sit at $17 or below, and the stock already trades within a dollar of them. If the second-quarter report confirms the Vans recovery, those older targets could move up. If it does not, the upgrades of the past week could look early. Price targets are estimates of what a security might be worth over a twelve-month horizon under a specific set of assumptions. They are not certainties.
52-Week High and Low Boundaries Analysis
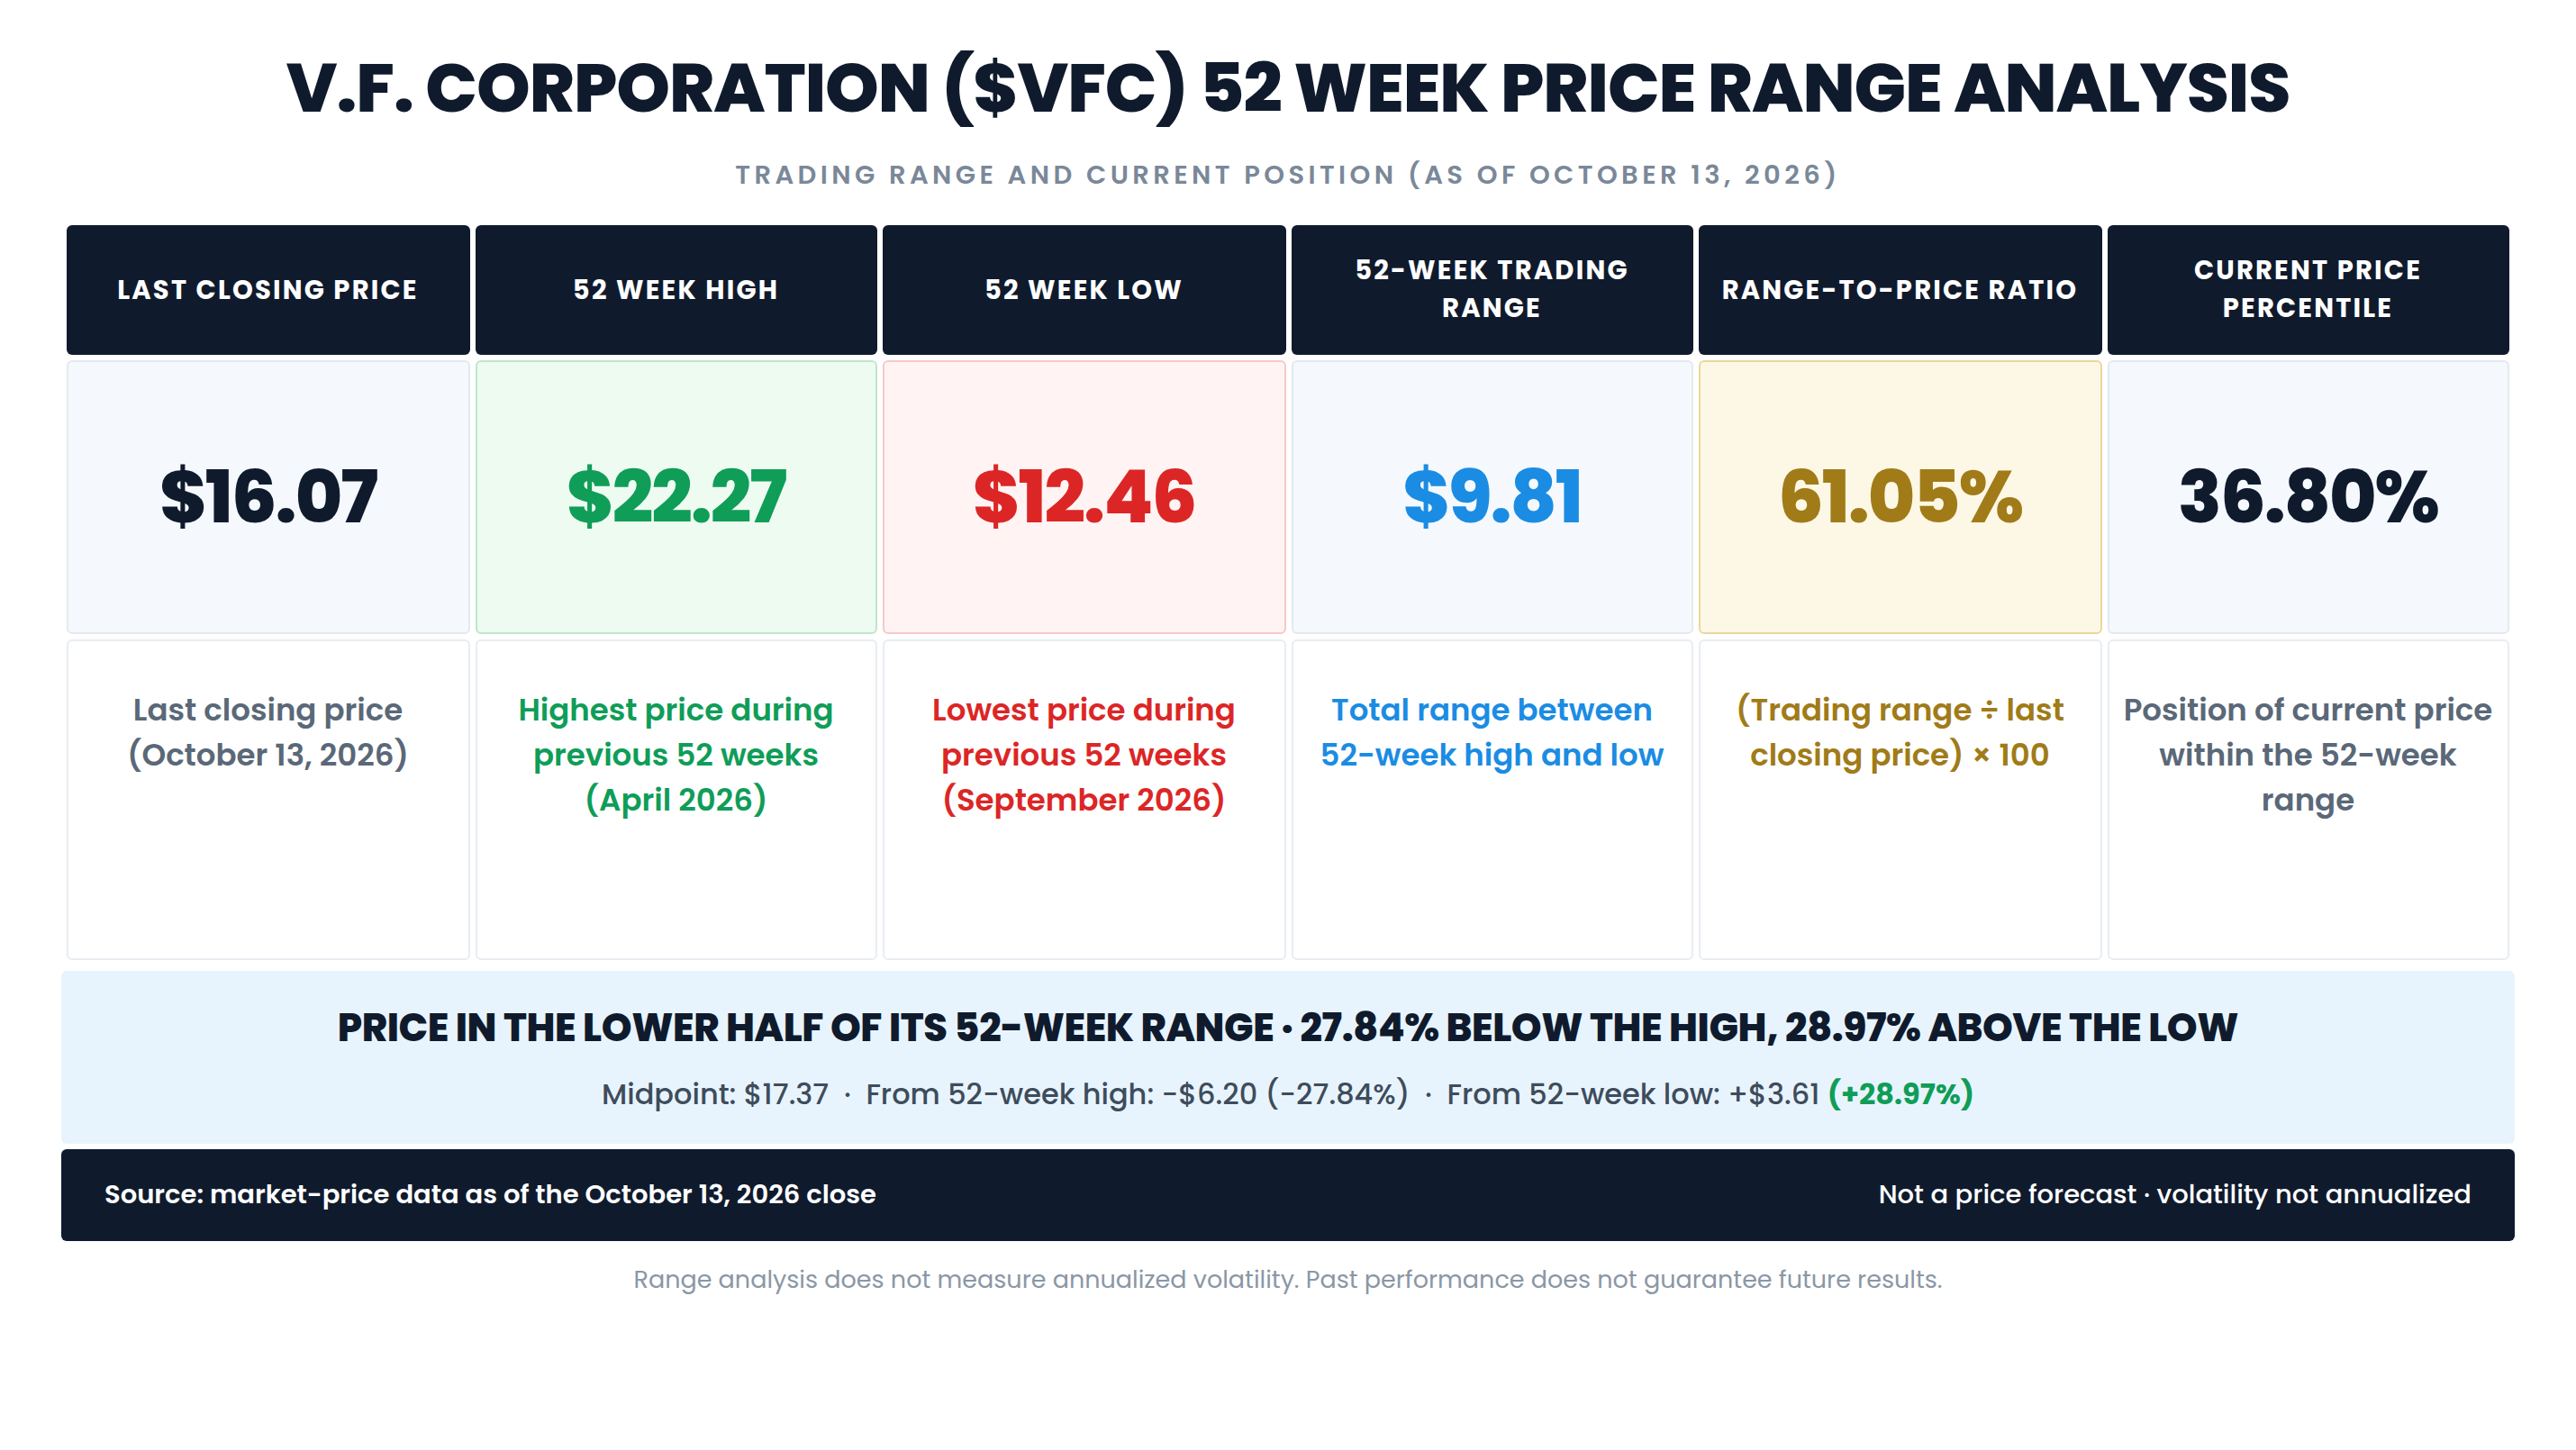
VF’s 52-week high is $22.27, set on April 21, 2026, and its 52-week low is $12.46, set on September 10, 2026.
The 52-week trading range is $9.81. Divided by the $16.07 closing price, that produces a range-to-price ratio of 61.05%, meaning the distance between the year’s high and low is more than half of today’s share price. The stock sits at the 36.80th percentile of its range. The midpoint of the range is $17.37, and the October 13 close is 7.46% below that midpoint. The stock needs a 38.58% gain to reach the 52-week high, and it is 28.97% above the 52-week low.
That combination is the defining feature of the setup. Four weeks ago, VF was trading at the very bottom of its range. The recovery since has lifted it more than a third of the way back, but it remains in the lower half of the range and below the $17.37 midpoint. Reclaiming the midpoint would be the first sign that the rebound is becoming a recovery rather than a bounce. Failing below it would keep the stock in the lower half of a range that has defined the past six months.
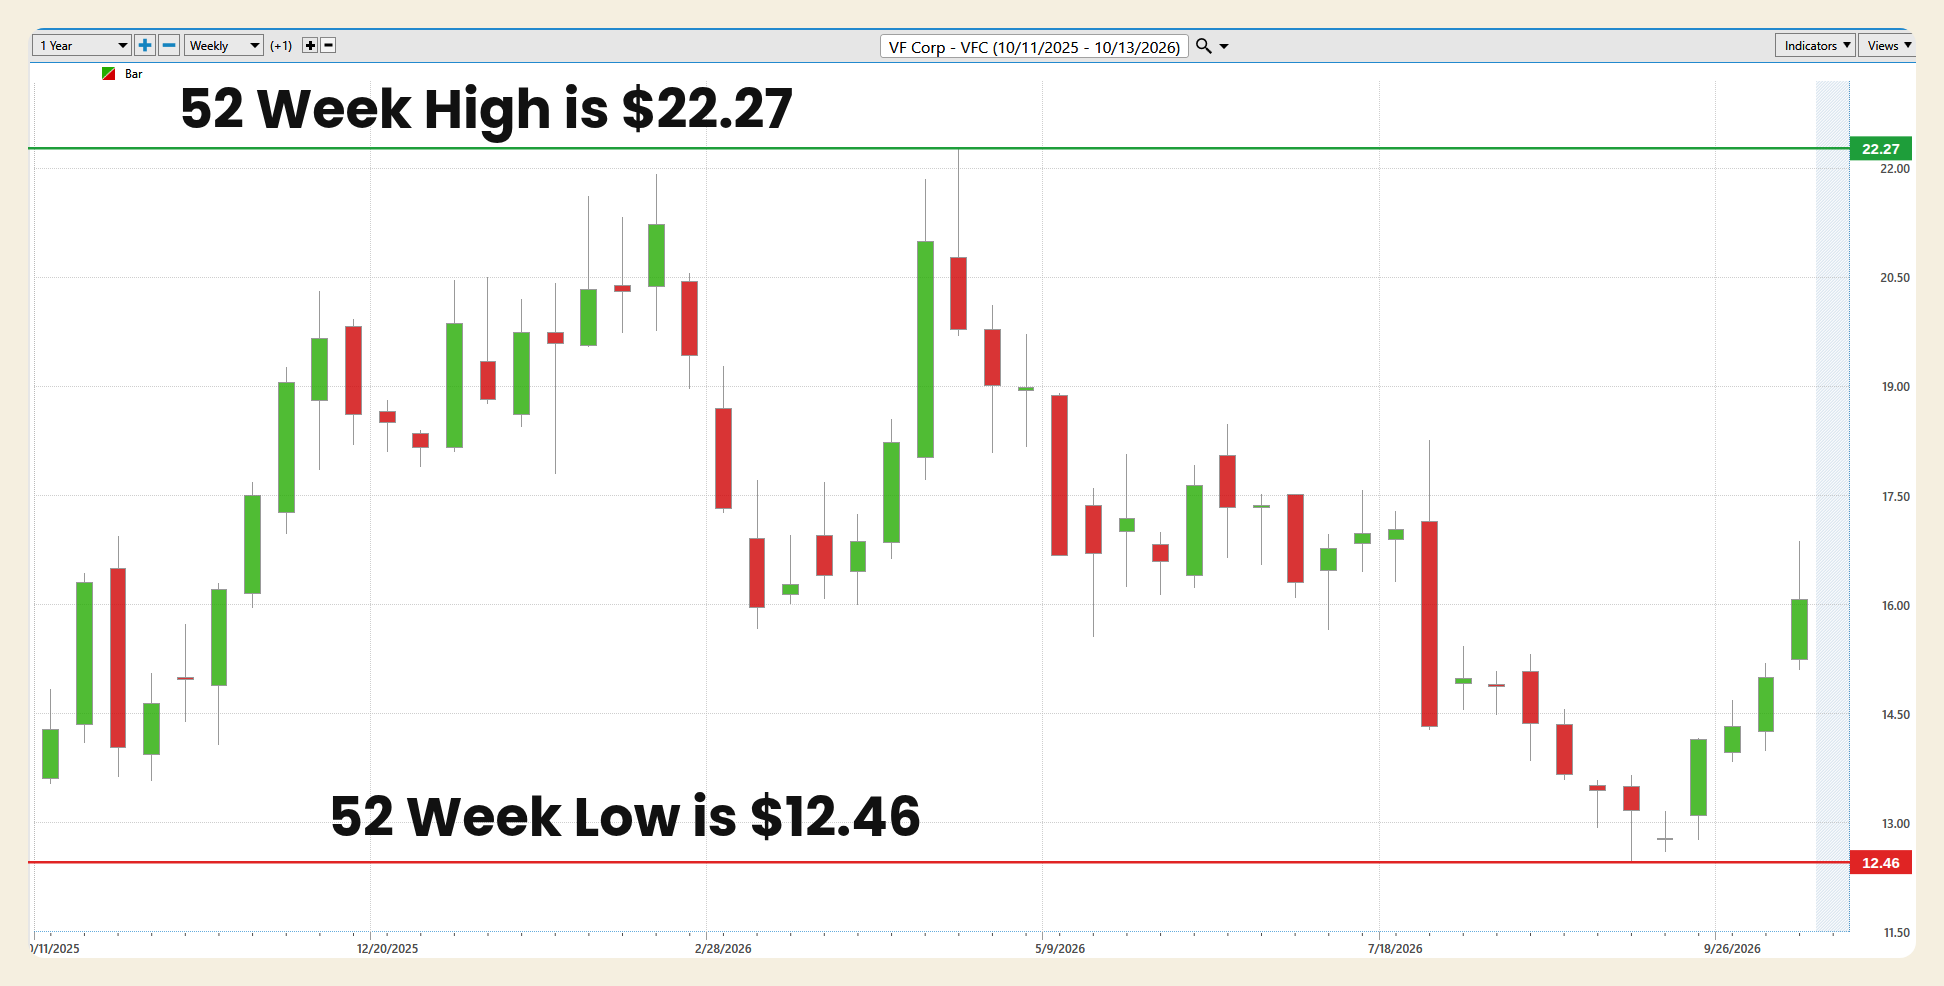
The one-year weekly chart shows a full round trip and the start of a second rally. From the October 2025 lows in the $13.60 to $14 area, VF rallied through November and December, closing December 2025 at $18.08 and January 2026 at $19.59, with a weekly high of $21.92 in late February. The stock then broke down in March, closing the month at $16.99, before staging a sharp April rally to the $22.27 high on April 21. That was the peak. From May through mid-July the stock drifted in a range between roughly $16 and $18.50, and then the late-July earnings week produced the largest red candle on the chart, sending the stock from the low $17s to the low $14s. August and early September extended the decline with a series of lower weekly highs and lower weekly lows down to the $12.46 low. The final candles show four consecutive green weeks, the latest of which reached $16.87 before closing at $16.07. The pattern is a wide range with violent swings in both directions, and the stock is now testing the middle of it from below.
Best-Case/Worst-Case Analysis
The best-case historical moves are large. From its April 9, 2025 intraday low of $9.41, during the tariff-driven market decline, VF rose 136.66% to its April 21, 2026 high of $22.27. From its November 4, 2025 low of $13.58, it rose 61.41% to its February 20, 2026 high of $21.92. Most recently, it has gained 28.97% from the September 10, 2026 low to the October 13 close in 23 trading sessions, and it reached 35.39% above that low at the October 13 intraday high of $16.87.
The worst-case historical moves are larger. From its April 29, 2021 high of $90.79, VF fell 89.64% to the April 9, 2025 low of $9.41, a four-year collapse that erased most of the stock’s value as revenue shrank and the company cut its dividend. Inside the current window, from the April 21, 2026 high of $22.27, the stock fell 44.05% to the September 10 low of $12.46. Single sessions have been just as severe: VF fell 28.74% on April 3, 2025 and 17.37% on July 29, 2026.
Historical gains are not forecasts, and historical losses are not predictions. What these figures show is that this stock has real capacity for movement in both directions, and that even after the balance sheet repair of the past two years, a single earnings report can still move it by more than 15%. Position sizing and an exit plan matter, particularly with the October 28 report two weeks away.
The condition that keeps the bull case alive is follow-through above the midpoint: the stock holding above the October 12 close of $15.79, reclaiming the $17.37 midpoint of its 52-week range and building toward the $18 to $19 area where it spent much of May and June, while second-quarter results confirm that Vans wholesale is improving on schedule. The change of character that would invalidate the thesis is a close back below the September 10 low of $12.46. That would resume the summer’s sequence of lower highs and lower lows, and it would mean the market had rejected both the balance sheet progress and the upgrade cycle.
The upside opportunity is substantial but contingent.
Relative Strength Comparison
VF has lagged most major U.S. benchmarks over the longer periods measured and has sharply outperformed all four over the shorter ones. All figures are price returns.
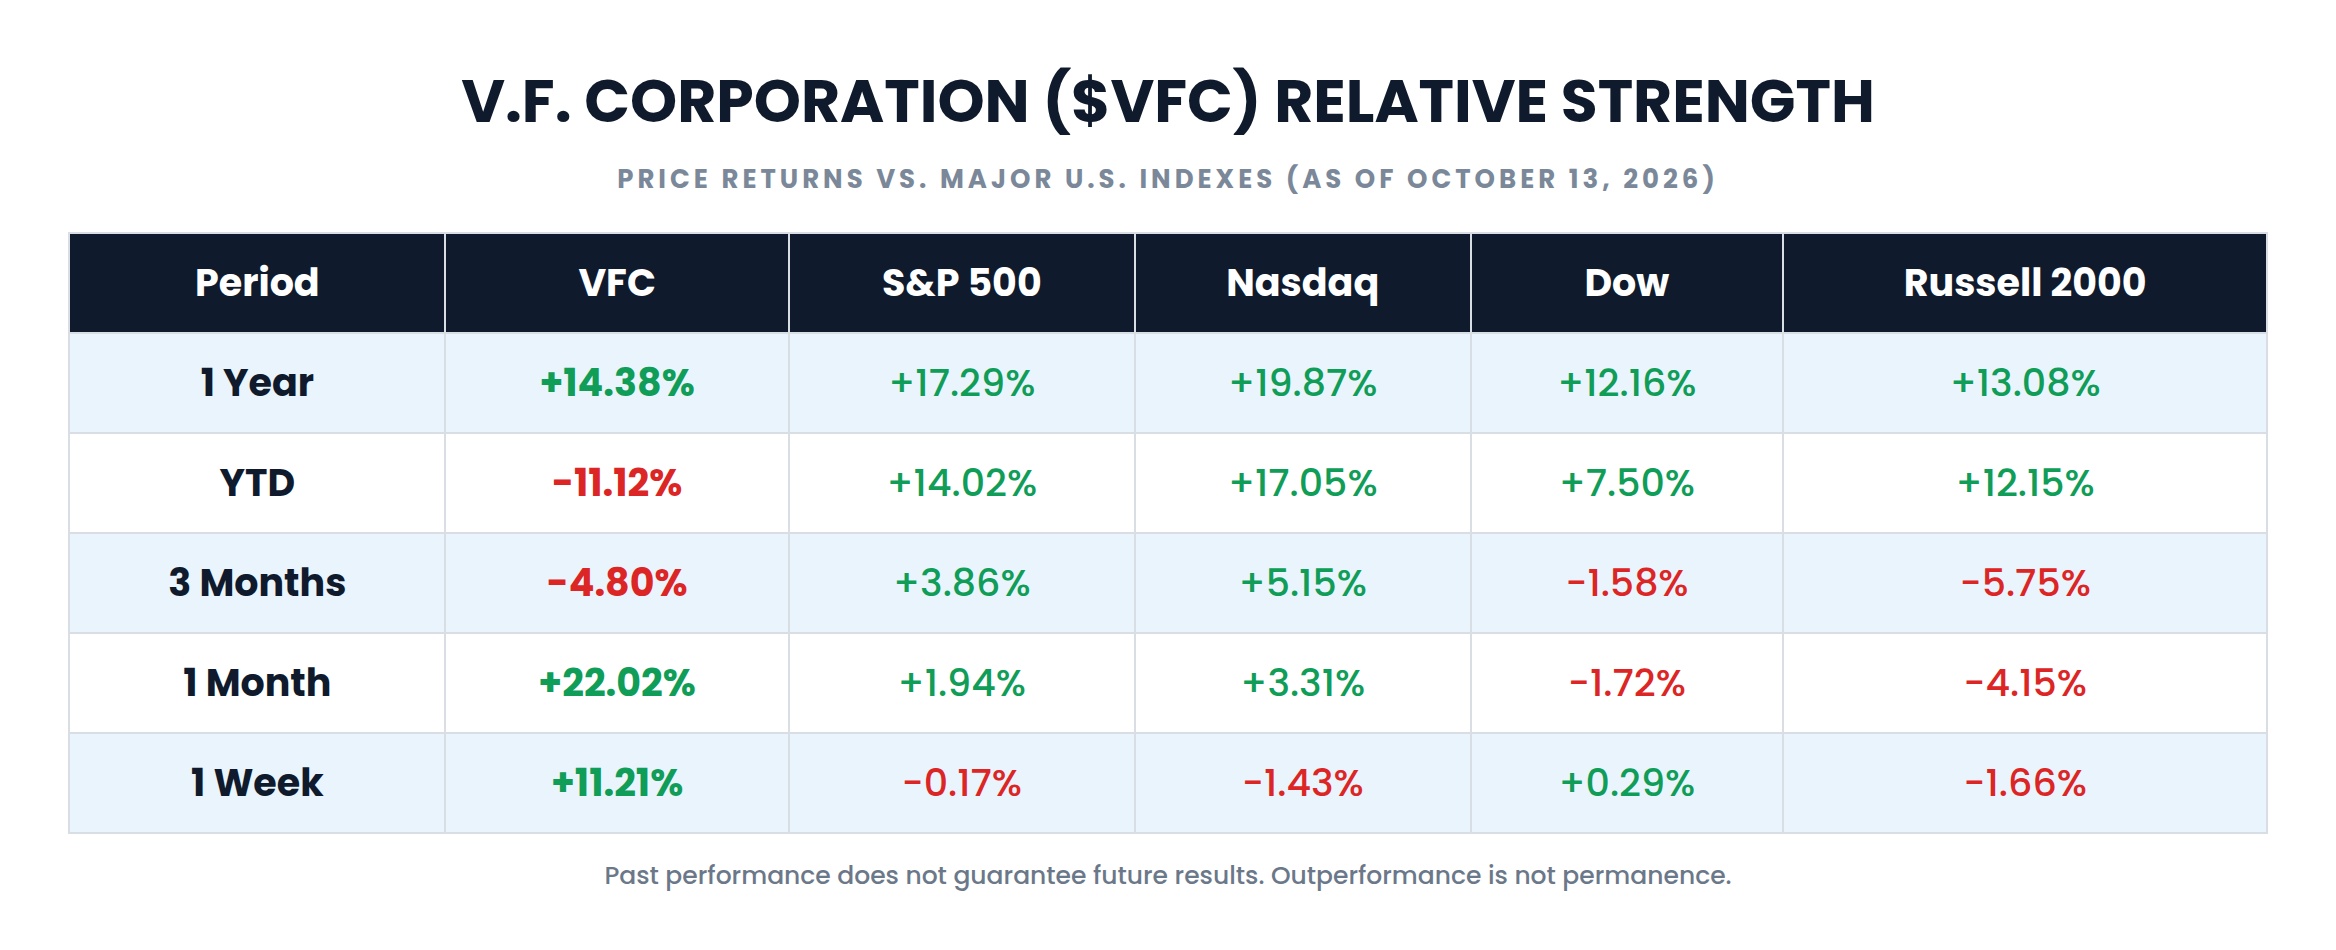
Returns are measured to the October 13, 2026 close from these starting closes: 1 Year, October 13, 2025; YTD, December 31, 2025; 3 Months, July 13, 2026; 1 Month, September 11, 2026; 1 Week, October 6, 2026. Nasdaq refers to the Nasdaq Composite and Dow refers to the Dow Jones Industrial Average.
This is a laggard-to-leader reversal pattern. Over the past year, VF’s 14.38% gain trailed the S&P 500 and the Nasdaq but edged out the Dow and the Russell 2000, mostly because the stock started the window near its lows. Year to date, it is down 11.12% while every index is up between 7.50% and 17.05%, a gap of more than 28 percentage points against the Nasdaq. Over three months, it is down 4.80%, trailing three of the four benchmarks and edging only the Russell 2000. Then the picture flips. Over the past month, VF rose 22.02% while the S&P 500 gained 1.94% and the Dow and Russell 2000 both fell. Over the past week, it rose 11.21% while no index gained more than 0.29%.
It is worth being precise about what this kind of relative strength means. Short-window leadership after a long stretch of underperformance is often a rebound from oversold levels, and much of the past week’s gain came in three sessions around the analyst upgrades. Rebounds can turn into new trends, but they need confirmation over weeks, not days, and VF’s next confirmation test is a scheduled earnings report. Outperformance is not permanence.
VantagePoint AI Predictive Blue Line
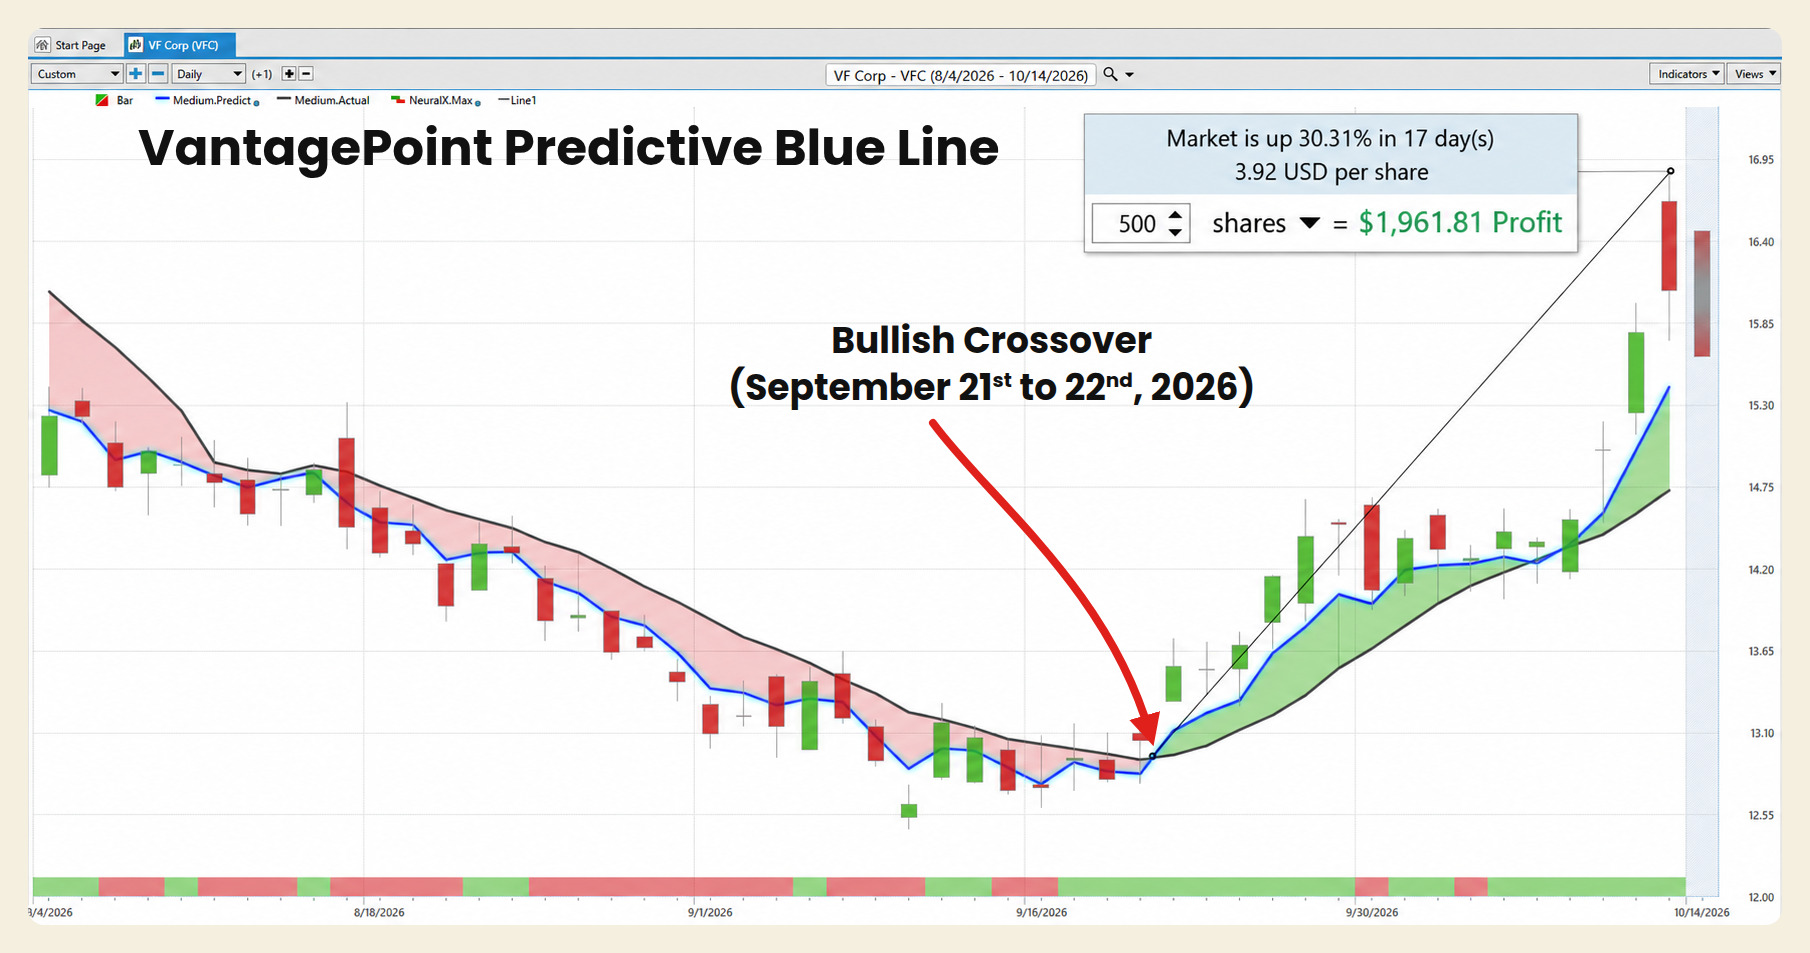
The VantagePoint AI Predictive Blue Line is a forecasted moving average that uses artificial intelligence to anticipate where the trend is heading, rather than simply reporting where it has been. The key reading is the relationship between the blue line and the black line, which represents the actual moving average of price. When the blue line is above the black line and rising, the forecast is pointing to strength ahead. When it crosses below, the forecast is warning of weakness.
The chart covers August 4 through October 13, 2026, with the forecast extending to October 14. Through all of August and the first three weeks of September, the Predictive Blue Line sat below the black actual moving average, and the band between them was shaded red as the stock slid from the $15 area toward its lows. The two lines converged in mid-September near $12.90. The blue line then crossed above the black line between the September 21 and September 22 sessions, and the shading turned green. That bullish crossover arrived when the stock was still closing below $13.60, within about 9% of its 52-week low and three weeks before the analyst upgrades made headlines.
Since the crossover, the blue line has stayed above the black line, and the green band has widened through the October rally. By the October 13 session, the Predictive Blue Line read approximately $15.41 while the black actual moving average read approximately $14.71, a gap of about $0.70, or roughly 4.8%. The slope of the blue line steepened noticeably over the final four sessions. VantagePoint’s own measurement on the chart shows the market up 30.31%, or $3.92 per share, over 17 days, measured from the September 21 low area to the October 13 high.
The distinction matters. The Blue Line turned before the big move, not because of it, which is exactly what a forecasted moving average is designed to do. The current reading is bullish, with a rising forecast and a widening separation. It is also worth noting that the October 13 close of $16.07 sits well above both lines, which tells you price has run ahead of even the forecasted trend. The reading that would change the picture is a flattening of the blue line followed by a cross back below the black line.
VantagePoint AI Neural Index
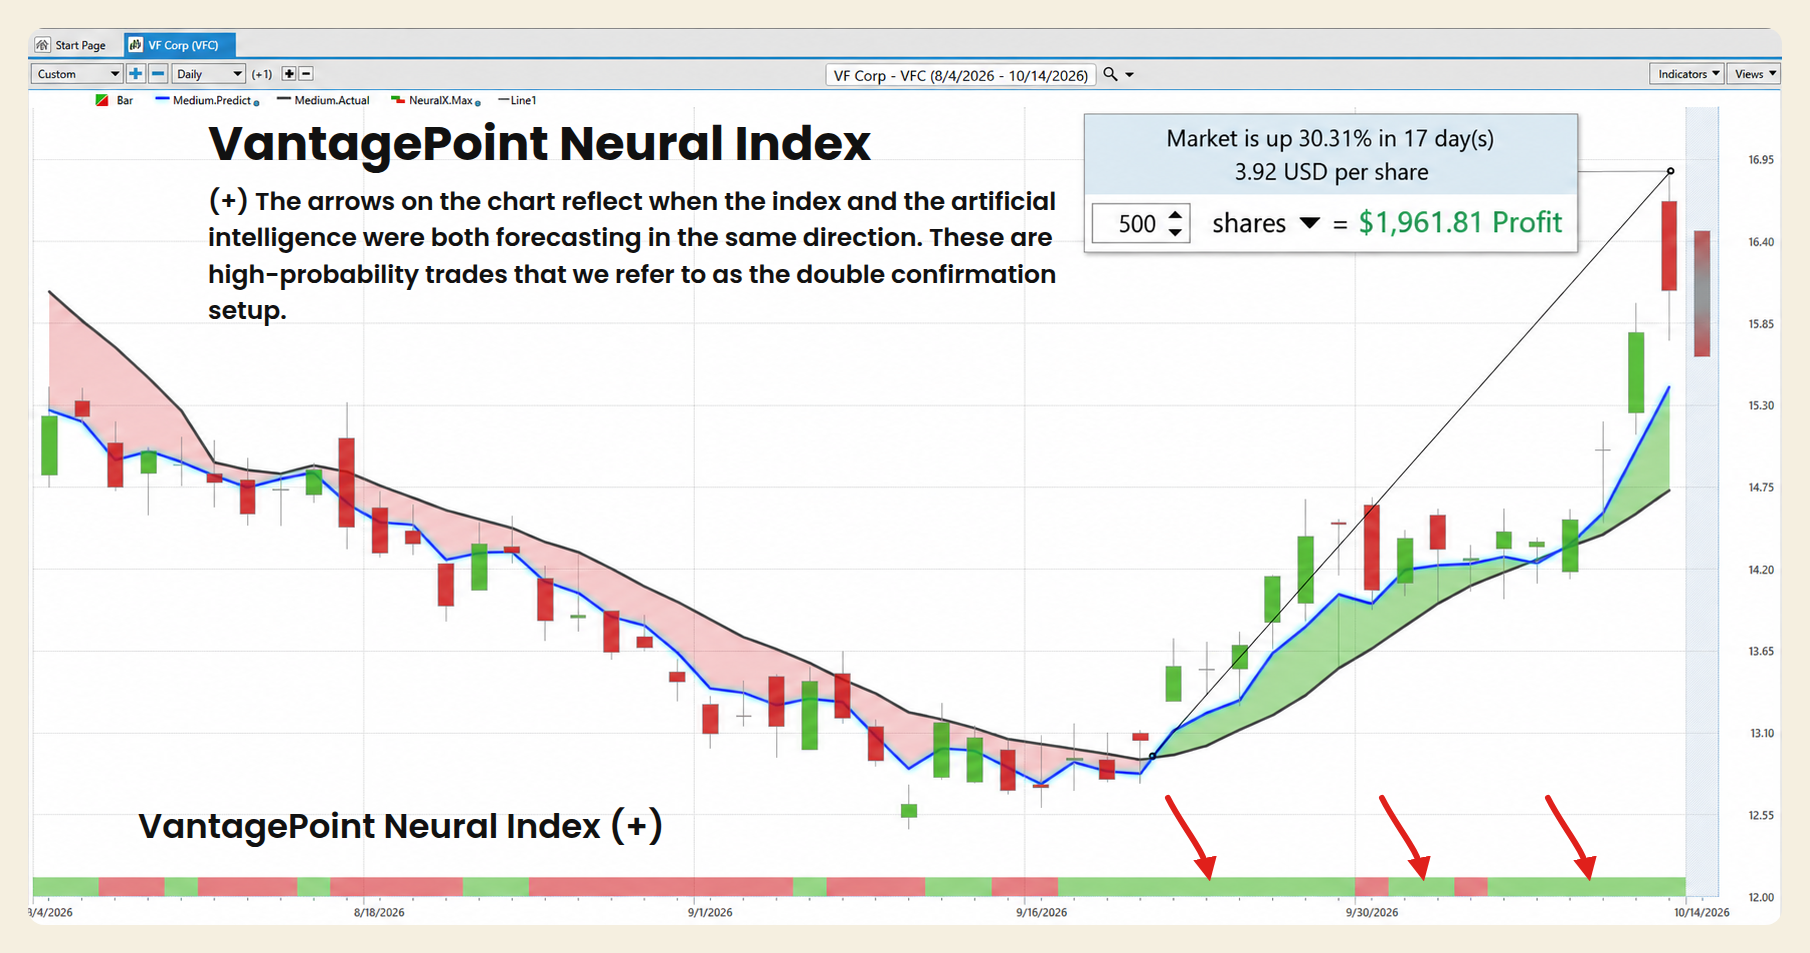
The VantagePoint AI Neural Index is a short-term strength indicator that forecasts whether the market is likely to be higher or lower over the next 48 hours. It appears as the colored strip along the bottom of the chart: green indicates predicted short-term strength and red indicates predicted short-term weakness.
The strip tells the story of a trend change. From early August through mid-September, the Neural Index alternated between short green runs and longer red runs, including an eight-session red stretch from August 25 through September 3 as the stock fell toward its lows. The last red stretch of the decline came on September 15 and 16. From September 17 through October 13, the Neural Index was green in 17 of 19 sessions, with single red readings on September 30 and October 5. Each of those red readings was followed by a return to green the next session, and the October 5 reading was followed by six consecutive green sessions into the upgrade rally.
When the Neural Index and the Predictive Blue Line agree, VantagePoint refers to the setup as a double confirmation. From September 22 onward, with the blue line above the black line, the Neural Index has been green in every session except September 30 and October 5, which produced the three double confirmation stretches marked on the chart: September 22 through September 29, October 1 and 2, and October 6 through October 13. The item to watch is the next red reading. After six straight green sessions and an 11.21% weekly gain, a red print would be the earliest sign that short-term momentum is cooling, even if the Blue Line still points higher.
VantagePoint AI Daily Range Forecast
The VantagePoint AI Daily Range Forecast projects a predicted high and a predicted low for the next trading session. The red line marks the predicted high and the dark line marks the predicted low. Together they frame where price is expected to trade, giving traders a structure for entries, exits and stop placement.
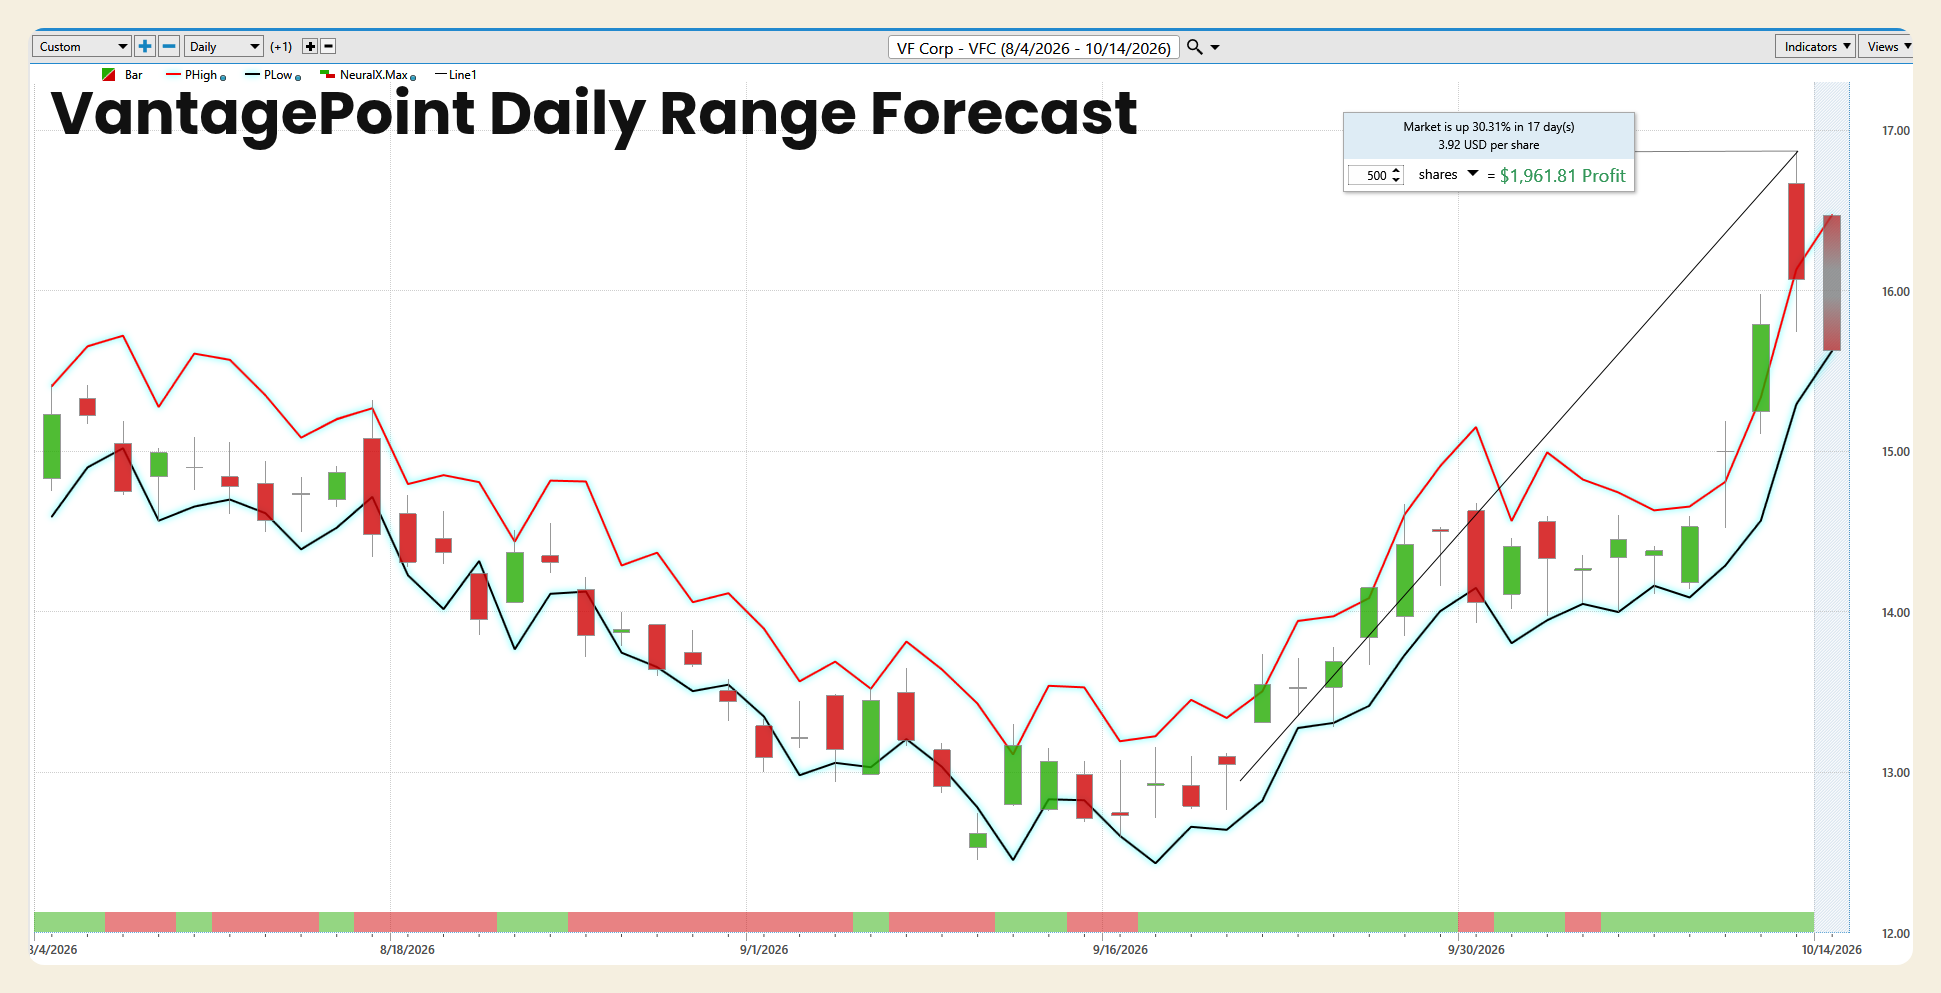
For October 14, 2026, the forecast bar spans from a predicted high of approximately $16.47 to a predicted low of approximately $15.63, a projected range of about $0.84, or 5.23% of the October 13 close. That is wider than the stock’s recent behavior: across the past 20 sessions, VF’s average daily range was 3.80% of its closing price. The forecast is expecting an active session. The October 13 close of $16.07 sits almost exactly at the roughly $16.05 midpoint of the projected band.
The more important observation is the direction of both boundaries. The predicted high and predicted low have been rising since the September 16 low area, and both turned sharply higher over the final week of the chart. When both boundaries rise together, the forecast is describing a trending market rather than a range-bound one. The October 13 session also shows how stretched the move became. The predicted high for that day was approximately $16.15, yet the stock opened at $16.67, above the entire projected band, before falling back inside it to close at $16.07. An open that far outside the projected range is a sign of strong momentum, and the same-day retreat marks a short-term zone where pullbacks become more likely.
For a trader, the practical use is straightforward. A pullback toward the predicted low, near $15.63 for October 14, would be a test of the short-term trend rather than a break of it. A close below the predicted low, especially on a day when the Neural Index turns red, would be the first sign that the rising structure is weakening. Upper-band trading near $16.47 is the zone where short-term traders tend to tighten stops rather than chase.
Intermarket Analysis
No stock trades in isolation. VantagePoint’s Intermarket Analysis identifies the related markets whose price behavior has the greatest influence on the forecast for a given stock, and it feeds those relationships into the AI models behind the readings above.
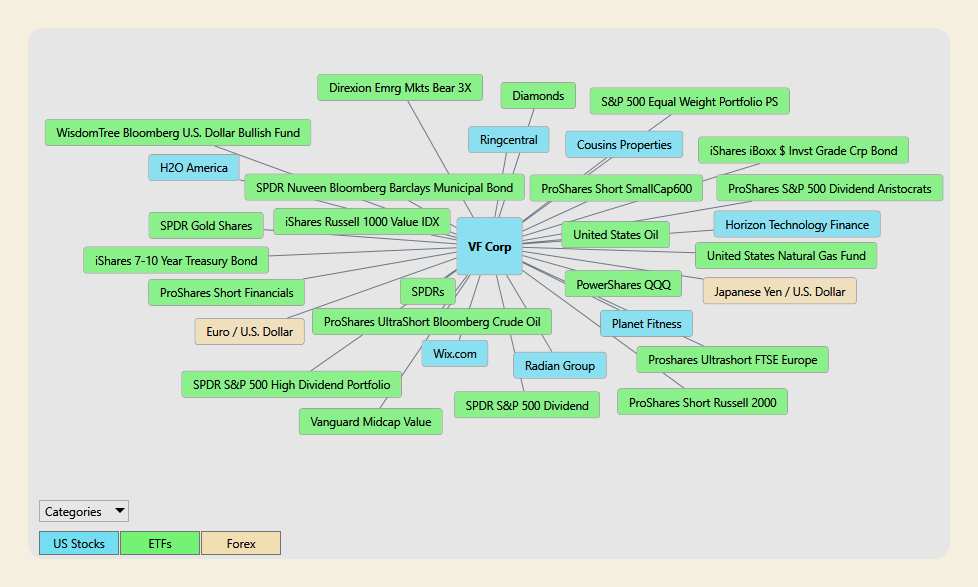
For V.F. Corporation, the map includes 7 U.S. stocks, 22 exchange-traded funds and 2 currency pairs. The U.S. stocks are RingCentral, Cousins Properties, H2O America, Horizon Technology Finance, Planet Fitness, Wix.com and Radian Group. The ETFs are the Direxion Emerging Markets Bear 3X fund, Diamonds, the S&P 500 Equal Weight Portfolio, the WisdomTree Bloomberg U.S. Dollar Bullish Fund, the iShares iBoxx $ Investment Grade Corporate Bond fund, the SPDR Nuveen Bloomberg Barclays Municipal Bond fund, ProShares Short SmallCap600, ProShares S&P 500 Dividend Aristocrats, SPDR Gold Shares, the iShares Russell 1000 Value Index fund, United States Oil, the iShares 7-10 Year Treasury Bond fund, the United States Natural Gas Fund, ProShares Short Financials, SPDRs, PowerShares QQQ, ProShares UltraShort Bloomberg Crude Oil, ProShares UltraShort FTSE Europe, the SPDR S&P 500 High Dividend Portfolio, the SPDR S&P 500 Dividend fund, ProShares Short Russell 2000 and Vanguard Mid-Cap Value. The currency pairs are the euro against the U.S. dollar and the Japanese yen against the U.S. dollar.
What stands out is how few of the related markets are apparel companies. The map leans heavily on market style and macro factors rather than on direct competitors. The value and income funds, including the iShares Russell 1000 Value fund, Vanguard Mid-Cap Value, the Dividend Aristocrats fund and the two SPDR dividend funds, reflect the fact that VF trades as a beaten-down, dividend-paying value stock, and its price tends to respond when money rotates toward or away from that corner of the market. The small-cap and equal-weight funds, along with the inverse small-cap and inverse Russell 2000 funds, capture the same idea from a different angle: VF’s market value of about $6.3 billion places it closer to the mid-cap end of the market, where breadth and risk appetite matter.
The rate and currency entries matter just as much. The iShares 7-10 Year Treasury Bond fund, the investment-grade corporate bond fund and the municipal bond fund connect to interest rates and credit conditions, which are relevant for a company carrying about $3.0 billion of long-term debt and working to lower its leverage ratio. The dollar fund and the euro and yen pairs connect to currency translation, which matters for a company that reports both reported and constant-currency results across the Americas, Europe and Asia-Pacific. The inverse FTSE Europe fund and the inverse emerging markets fund extend that international link. Among the individual stocks, Planet Fitness is the clearest consumer connection, while Cousins Properties, Radian Group and H2O America capture interest rate sensitive real estate, housing finance and utility exposure. The energy funds, including United States Oil, the United States Natural Gas Fund and the inverse crude oil fund, along with SPDR Gold Shares, describe the broader commodity and inflation backdrop.
The distinction matters. Intermarket Analysis does not claim that any one of these markets moves VF on a given day. It recognizes that a consumer brand company in the middle of a turnaround is exposed to interest rates, currencies, value and income rotation and the broader risk appetite of the market all at once, and it lets the AI weigh those influences together rather than asking a trader to track 31 charts by hand.
Our Suggestion
V.F. Corporation is a company where two honest stories are true at the same time. The first is a century-old brand owner whose revenue is still 18.89% below its 2022 peak, whose largest youth brand is still shrinking, which missed earnings estimates last quarter, is changing chief financial officers and just rallied on analyst upgrades rather than on new results. The second is a company that has cut its leverage ratio from 5.1x to 3.1x in two years, returned to annual revenue growth, expanded margins, sold two brands for roughly $2.1 billion of announced value and now has The North Face and Timberland growing while Vans shows its first direct-to-consumer growth in the Americas in more than four years. The market spent the spring and summer giving more weight to the first story. In the past month, it has started giving more weight to the second.
That is the trade in one sentence: VF is a bet that a deleveraged portfolio of outdoor brands can carry the company long enough for Vans to stabilize, and the bet holds only if the October 28 report and the quarters after it confirm the recovery that analysts are now pricing in.
The weekly chart frames the opportunity and the risk. VF sits at the 36.80th percentile of its 52-week range, 7.46% below the $17.37 midpoint, with 38.58% of room to the $22.27 high and 22.46% of downside to the $12.46 low. The stock has made one full round trip from the April high to the September low, and the October rally has recovered a little over a third of that decline. Four green weeks broke the summer pattern of lower highs, but the stock has not yet reclaimed the middle of its range.
Taken together, the VantagePoint readings are aligned. The Predictive Blue Line crossed above the black line between September 21 and 22 and has widened its lead since, reading about $15.41 against $14.71 at the end of the chart. The Neural Index has printed green in 17 of the last 19 sessions, including six in a row, giving three double confirmation stretches since the crossover. The Daily Range Forecast shows both boundaries rising, with a projected band of approximately $15.63 to $16.47 for October 14. The short-term forecasting tools are pointing in the same direction as the one-month and one-week relative strength data.
The risks are clear. The October 28 earnings report is two weeks away, and the last report produced a 17.37% single-day decline. Management has already guided to another roughly 9% decline in Vans for the quarter, so the market will be judging the second-half recovery outlook more than the quarter itself. Most neutral price targets sit between $16 and $18, near the current price. On the chart, the October 13 session opened above the entire predicted range, faded back inside it and filled the gap intraday, which means price is stretched in the short term. Momentum is not safety, and a stock that can gain 29% in a month can give back a large share of that just as quickly, as it did when it fell 44.05% from April to September.
For traders, the disciplined approach is to let the VantagePoint readings define the risk rather than the headlines. A Neural Index turning red, a flattening Predictive Blue Line or a close below the predicted low would each be a reason to tighten risk. A close back below the October 12 close of $15.79 would suggest the upgrade rally is fading, and a close below the September 10 low of $12.46 would indicate that the character of the trend has changed. Until then, the evidence favors respecting the rebound while keeping position size modest enough to absorb an earnings-sized move in either direction.
Historical returns and technical outputs are not guarantees of future results. They are tools for framing probability and managing risk.
Practice great money management on every trade, and use the VantagePoint AI Daily Range Forecast to identify short-term trading opportunities while keeping risk firmly under control.
It’s not magic.
It’s machine learning.
Disclaimer: THERE IS A HIGH DEGREE OF RISK INVOLVED IN TRADING. IT IS NOT PRUDENT OR ADVISABLE TO MAKE TRADING DECISIONS THAT ARE BEYOND YOUR FINANCIAL MEANS OR INVOLVE TRADING CAPITAL THAT YOU ARE NOT WILLING AND CAPABLE OF LOSING.
EXAMPLES ARE SUCCESS STORIES AND ATYPICAL. PAST RESULTS DO NOT GUARANTEE FUTURE PERFORMANCE.
VANTAGEPOINT’S MARKETING CAMPAIGNS, OF ANY KIND, DO NOT CONSTITUTE TRADING ADVICE OR AN ENDORSEMENT OR RECOMMENDATION BY VANTAGEPOINT AI OR ANY ASSOCIATED AFFILIATES OF ANY TRADING METHODS, PROGRAMS, SYSTEMS OR ROUTINES. VANTAGEPOINT’S PERSONNEL ARE NOT LICENSED BROKERS OR ADVISORS AND DO NOT OFFER TRADING ADVICE.